Michigan
Artichoke Credit Union Launches to Address Banking for People with Disabilities
It was another financial institution’s commercial that motivated me to create something different. Two busy white, apparently nondisabled, suburban parents were standing on their carefully manicured lawn talking about how they needed to go to the bank to plan for…

Last updated:
Key points
- Artichoke Credit Union will launch in early 2027 as a nationwide, member-owned institution serving people with disabilities.
- Roughly 30 percent of disabled Americans are unbanked or underbanked, facing higher financial barriers and fees.
- Major foundations funded the project to help close systemic economic disparities and expand accessible banking services.
NewsWK — Financial leaders across the nation are taking new steps to broaden economic access. These efforts will reach millions of households. In response to persistent economic disparities, a new nationwide institution is launching. Specifically, it aims to eliminate systemic barriers in mainstream banking. Artichoke Credit Union will provide specialized financial resources for individuals with disabilities. Furthermore, it will serve their family members and advocacy organizations.
How does Artichoke Credit Union plan to provide financial services for disabled people?
Artichoke Credit Union offers tailored banking products for individuals with disabilities and their families. the early second quarter of 2027 The member-owned institution provides checking accounts, personal loans, share certificates, and credit cards. Additionally, it integrates supported decision-making models, accessibility features, and financial education to ensure full community inclusion.
Traditional institutions often overlook accessibility. Consequently, this new entity operates as a member-owned cooperative. Therefore, account holders and community organizations directly own the institution. Organizers partnered with Michigan State University Federal Credit Union to build the operational infrastructure. That partner credit union already brings decades of experience. In fact, it has long served disabled students, alumni, and board members.
Additionally, members will utilize digital features designed for diverse needs. The platform will deliver custom account alerts, video services, and live phone assistance. Members can also consult an advisory board to guide future services.
Why is specialized banking for people with disabilities urgently needed today?
Millions of Americans with disabilities face severe structural barriers at traditional financial institutions. According to the National Disability Institute, nearly 30 percent of disabled individuals remain unbanked or underbanked. High fees and systemic discrimination leave many families economically vulnerable. Moreover, many people lack awareness regarding beneficial tools like ABLE accounts.
In contrast, only 17 percent of nondisabled Americans lack standard banking accounts. Financial analysts attribute this gap partly to a lack of institutional trust. Furthermore, households caring for disabled family members face higher living costs. Research indicates these families need nearly $20,000 in extra annual income for basic necessities. Consequently, many families turn to online crowdfunding. There, medical expenses account for one-third of campaigns.
To help residents navigate these burdens, the institution will offer a comprehensive suite of tools:
- Checking and savings accounts with low fees
- Personal loans and share certificates
- Custom debit and credit card options
- Financial literacy materials and budgeting resources
- Supported decision-making tools for account management
What local impact will closing the disability wealth gap have on American families?
Addressing financial disparities directly strengthens household stability. Moreover, it expands economic independence for millions of families nationwide. Enhanced access to low-cost credit and savings tools helps individuals build long-term wealth. It also helps them run small businesses and reduce reliance on emergency fundraising platforms. Consequently, local communities gain economic resilience.
Economic disparities disproportionately affect disabled women and minority populations. The National Partnership for Women & Families recently studied this issue. For example, their research reveals that disabled women earn just 56 cents for every dollar earned by nondisabled men. They also experience higher rates of job displacement during economic downturns.
Poverty rates present a similarly stark picture across demographics. According to National Disability Institute reports, roughly 24 percent of white disabled adults live in poverty. However, that figure rises to 29 percent for Latine individuals. It reaches nearly 40 percent for Black disabled Americans. Meanwhile, some federal programs exclude disabled entrepreneurs from automatic eligibility. This includes the Small Business Administration’s 8(a) Business Development Program. Thus, dedicated capital helps bridge these compounding financial gaps.
What is the background behind Artichoke Credit Union and its mission for disability financial inclusion?
September Specifically, the Ford Foundation and the Robert Wood Johnson Foundation provided initial capital. The John D. and Catherine T. MacArthur Foundation also contributed grants. Ultimately, the credit union promotes financial inclusion by empowering members through cooperative ownership.
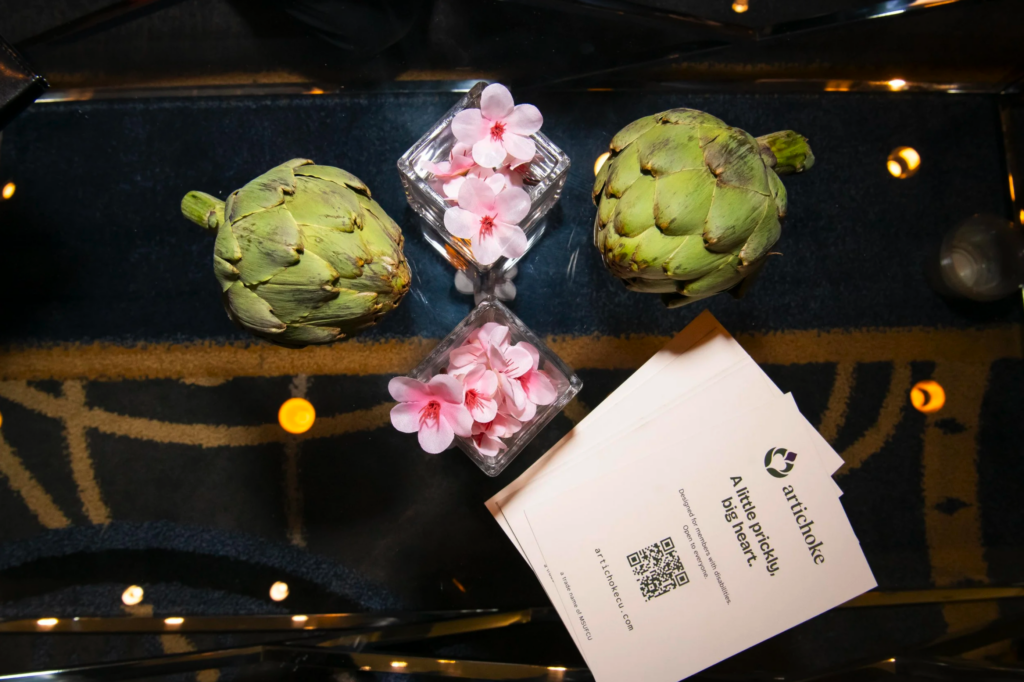
The institution derives its name from disability rights advocate Ed Roberts. Roberts contracted polio as a young man. Afterward, doctors told him that he would be a vegetable. However, he rejected that label and embraced a different identity instead.
“A little prickly on the outside, but with a big heart,” Roberts once explained. He added, “The vegetables of the world are uniting, and we’re not going away!”
Organizers conducted a landscape study with the Financial Health Network before launching the venture. As a result, that study identified priority gaps in credit access and savings vehicles. Finally, member sign-ups will officially open in the second quarter of 2027.
This article was produced with the assistance of AI and reviewed by our editorial team.
Sources
Related: Credit Union Investment Authority Act Introduced in Congress to Modernize Financial Rules
Related: Missouri Exits Multi-State Lawsuit on Disability Rights Protections
See a typo? Report it here.